










The Moment Europe’s Commercial and Industrial Storage Market Changed
Something fundamental shifted in the European energy storage market during the third quarter of 2026. It is not simply that installations are surging—though they are, with EUPD Research confirming a 78% year-on-year jump to 57 GWh across Europe this year. It is not merely that negative price hours have become a permanent feature of day-ahead markets from Spain to Finland. And it is not only that the EU Battery Regulation’s carbon footprint declaration has moved from a paperwork formality to a customs enforcement reality at Rotterdam and Hamburg.
The shift is this: the conversation has changed from “can storage make money?” to “how does storage make money reliably in a market defined by negative prices, grid congestion, and compliance complexity?”
For commercial and industrial (C&I) electricity users across Germany, Spain, the Netherlands, Italy, and the UK, the answer to that question now determines whether a project proceeds or stalls. A warehouse operator in Bavaria does not care about gigawatt-hour forecasts. They care whether a 500 kW / 1 MWh system will pay back before the next round of grid fee reform. A data centre developer in Amsterdam does not need another glossy market report. They need to know whether a battery system can bridge a seven-year grid connection wait while satisfying a 99.999% uptime requirement.
This guide is written for those operators, developers, and investors. It is not a market forecast. It is an operational reference—a working document for the questions that are actually blocking projects in September 2026.
Part I: The Market in Numbers—What September 2026 Actually Looks Like
1.1 The Scale of the Boom
EUPD Research’s September 2026 EES Report puts European battery storage installations at 57 GWh for the full year, up from 32 GWh in 2025. Germany, Bulgaria, Italy, the UK, and Spain lead growth, though for different reasons: Germany and Italy on mature installer ecosystems and policy frameworks; the UK and Spain on front-of-the-meter projects; Bulgaria on EU recovery fund momentum.
The C&I segment is the fastest-growing slice. In 2025, European C&I storage installations reached 4.7 GWh, a 77% year-on-year increase, representing 13% of annual additions. SolarPowerEurope projects C&I installations will reach 19.53 GWh by 2028, a compound annual growth rate of approximately 64% from 2024.
| Segment | 2025 (GWh) | 2026 (GWh, est.) | 2028 (GWh, proj.) | Key Driver |
| Residential | 11 | 15 | — | Self-consumption, dynamic tariffs |
| C&I | 4.7 | ~8 | 19.53 | Negative price arbitrage, capacity markets, grid constraints |
| Utility-scale | 16.2 | ~34 | — | Capacity auctions, front-of-meter |
| Total Europe | 32 | 57 | — | Policy + economics |
Sources: EUPD Research EES Report September 2026; SolarPowerEurope European Market Outlook 2024–2028.
1.2 Negative Prices: From Anomaly to Operating Condition
Germany recorded 573 negative price hours in 2025. By May 2026, the country had already logged 242 negative hours, tracking above the prior year’s pace. Spain’s Q1 2026 alone saw 347 negative-price hours, up from 73 in the same quarter of 2025—a near fivefold increase. The Netherlands hit −€85/MWh in July 2026, with intraday spreads exceeding €295/MWh between midday trough and evening peak.
The critical distinction for C&I operators is not the hour count but the depth and duration. Germany’s 2025 negative hours averaged −€10.89/MWh, with a minimum of −€250.32/MWh. Spain’s averaged just −€2.10/MWh with a minimum of −€15.00/MWh. A battery system optimised for German market conditions will behave very differently from one deployed in Spain.
Table 1: Negative Price Exposure by Market, 2025–2026
| Market | 2025 Negative Hours | Q1 2026 Negative Hours | Avg. Depth (2025) | Key Risk for Solar-Only Assets |
| Germany | 573 | ~45 (Q1) | −€10.89/MWh | Midday curtailment, revenue collapse |
| Spain | 556 | 347 | −€2.10/MWh | High frequency, low depth; arbitrage window narrow |
| France | 509 | — | — | Nuclear baseload coupling |
| UK | 362 | — | — | Wind-driven, less predictable |
| Netherlands | — | — | −€85/MWh (Jul. 2026 min.) | Extreme intraday spread |
Sources: pv magazine Europe negative price analysis, May 2026; Bundesnetzagentur SMARD data.
1.3 Grid Congestion: The Binding Constraint
Over €100 billion in clean energy projects are stuck in distribution grid connection queues across just eight European countries. The AFRY report commissioned by Beyond Fossil Fuels identifies 375 GW of renewable projects and 455 GW of battery storage projects waiting for connection. Germany alone has a significant share of that storage queue.
For C&I operators, the implication is immediate: if you are waiting for a grid connection, you are losing money. The average distribution system operator (DSO) now handles over 11,000 annual connection requests, with governance structures designed for a fraction of that volume.
1.4 Capacity Markets: Real Money, Real Conditions
Germany’s first capacity auction under the StromVKG framework opened in September 2026, offering 4.5 GW of long-duration capacity with 15-year contracts. The rules are specific and restrictive: battery storage systems qualify only if capable of continuous discharge for at least 10 hours, with a reduction factor of 0.58 for 10-hour systems (rising to 0.85 for 20-hour systems, the same factor assigned to combined-cycle gas turbines). Battery systems must also demonstrate 100% technical availability—compared to 85% for gas plants—and round-trip efficiency of at least 92%.
Spain’s capacity mechanism, approved by the European Commission in May 2026, mobilises up to €9 billion over 2026–2036, running at approximately €900 million per year. Italy’s MACSE auction cleared 10 GWh at an average of €12,959/MWh-year on 15-year contracts, with bids exceeding demand by more than four times.
The common thread: capacity markets are no longer a future policy discussion. They are a present revenue stream—but only for systems configured to qualify.
1.5 The Compliance Wall
Since February 18, 2026, carbon footprint declarations have been mandatory for industrial batteries exceeding 2 kWh capacity placed on the EU market. Since August 2026, EU customs has moved to substantive random inspection of these declarations and battery passport data, with multiple Chinese-origin storage containers detained at Rotterdam.
The three failure points are consistent: carbon footprint calculations that do not follow EU Product Environmental Footprint (PEF) methodology; green electricity certificates that cannot be tied to specific production batches; and incomplete traceability documentation for lithium, nickel, cobalt, and natural graphite.
Part II: The Twelve Questions That Determine Whether Your Project Proceeds
Question 1: How Do You Turn Negative Prices from a Threat into a Revenue Stream?
The problem. A solar-only C&I installation in Germany now faces midday hours when exporting power costs the owner money. The investment payback period for pure PV has stretched beyond 10 years in many configurations. Summer curtailment rates reach 11% in high-penetration areas. The asset is producing energy that the market does not want at the moment of production.
The solution architecture. A battery system coupled to the PV array changes the physics of the problem. The EMS monitors day-ahead and intraday prices from EPEX SPOT or Nord Pool. When the price signal goes negative—or approaches zero with a forecast of negative clearing—the system diverts PV generation to battery charging rather than grid export. The stored energy is dispatched during evening peak hours, when Dutch prices have exceeded €210/MWh against midday troughs of −€85/MWh.
The critical requirement is not battery capacity alone. It is EMS logic that treats negative prices as a charging trigger, not a curtailment event. A system that simply follows a fixed charge-discharge schedule will miss the majority of negative-price arbitrage opportunities. The EMS must ingest market price feeds, weather forecasts, and load predictions, and adjust charge/discharge decisions on a 15-minute or hourly basis.
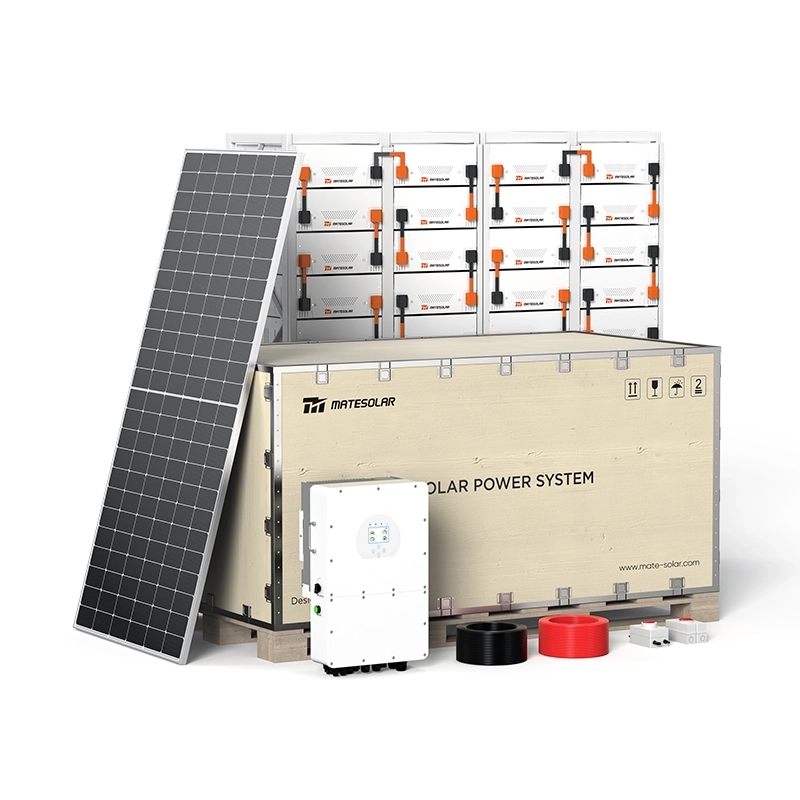
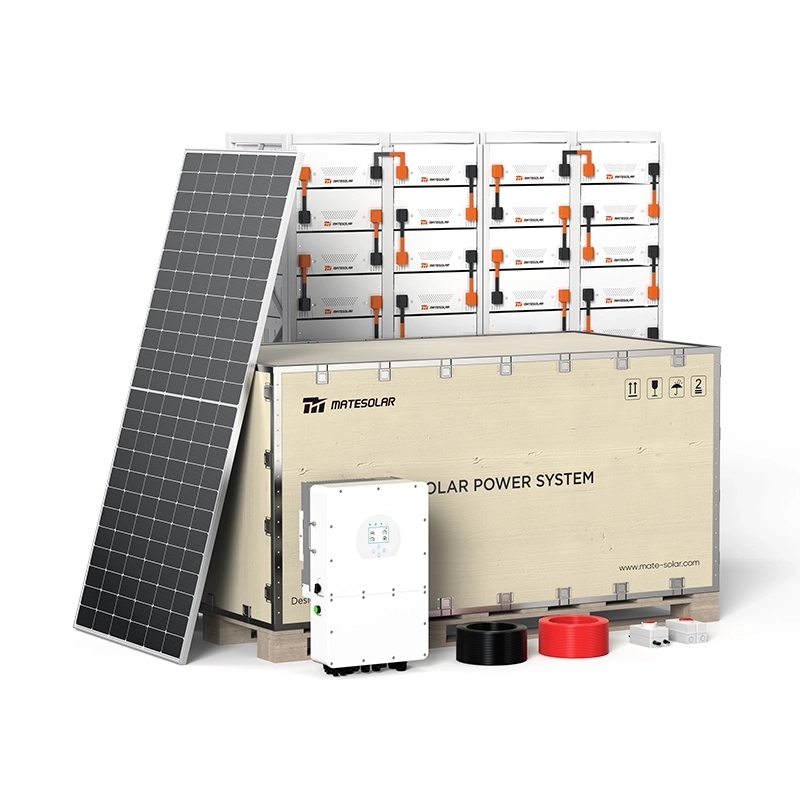
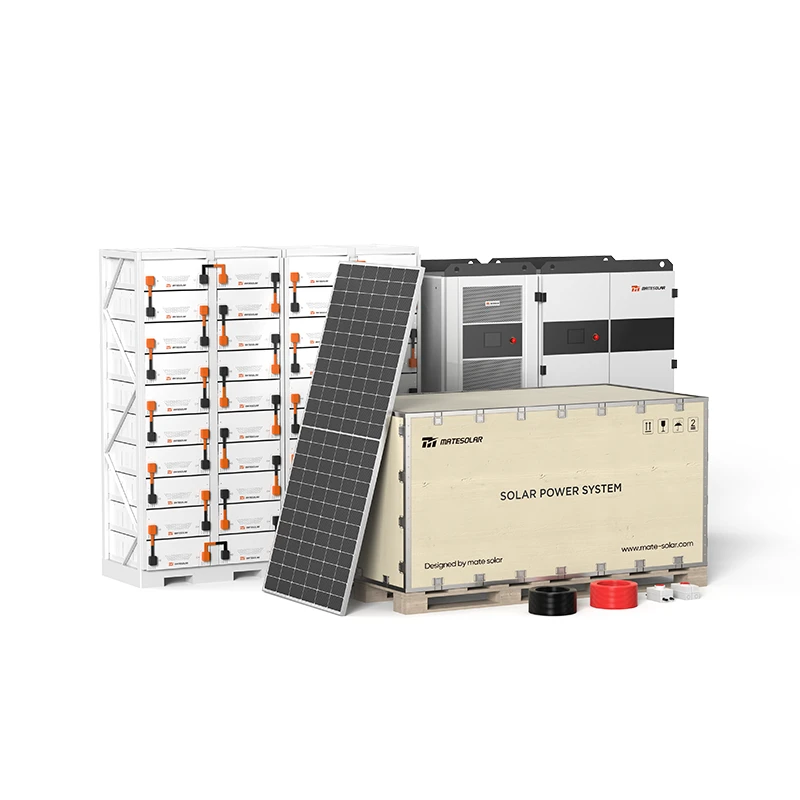
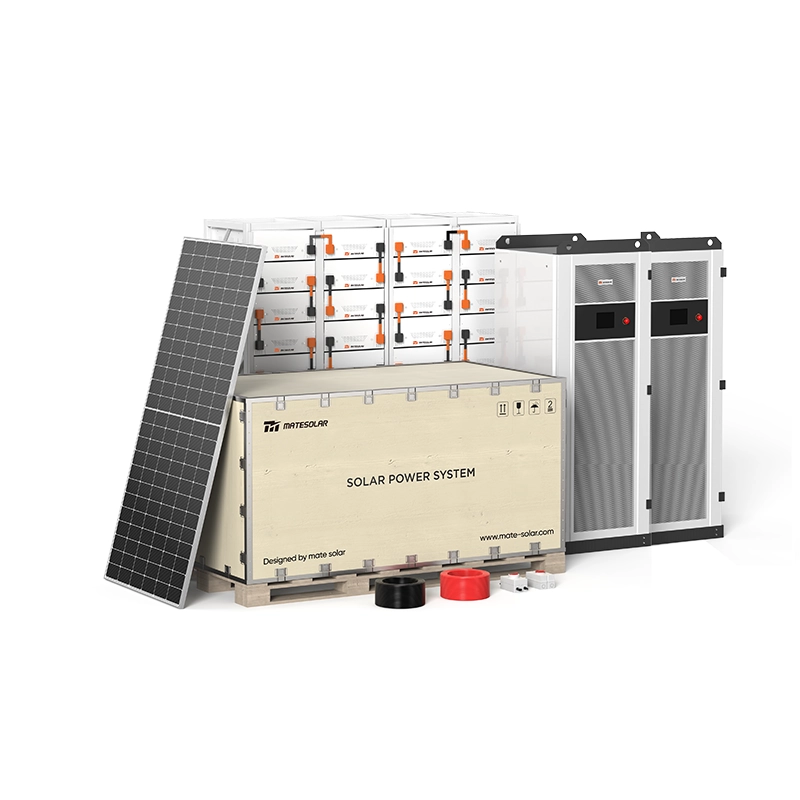
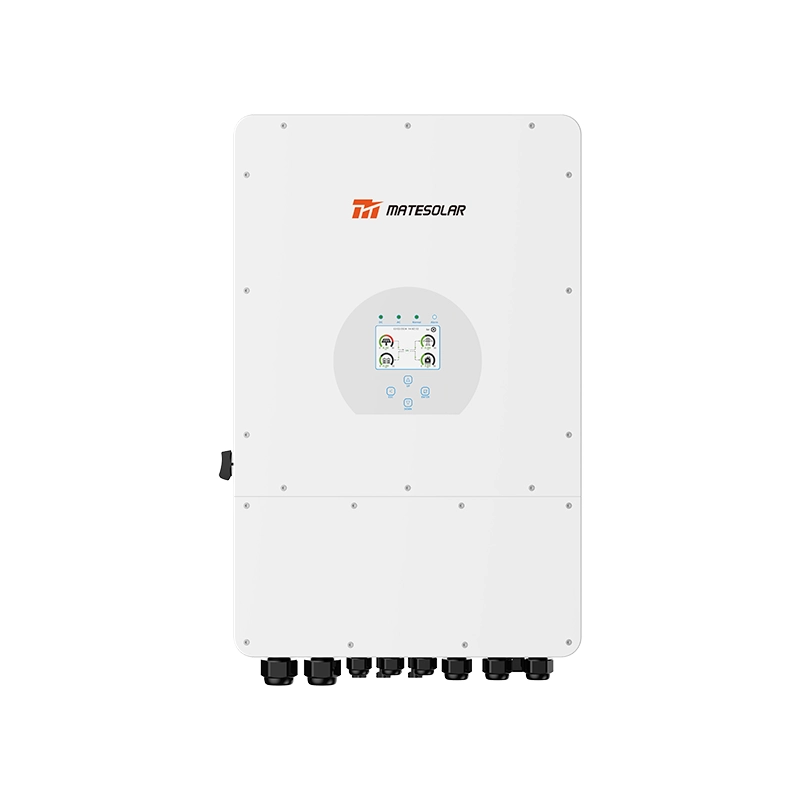
For C&I sites with 500 kW-class demand, a hybrid solar-plus-storage configuration provides the flexibility to both self-consume and arbitrage. The Commercial 500KW Hybrid Solar System is designed for this dual-mode operation, integrating PV input, battery storage, and grid interaction through a single control layer. In markets where negative-price hours are concentrated in the midday solar peak, the ability to shift that generation to evening dispatch is the difference between a marginal and a strong business case.
Table 2: Negative-Price Arbitrage Economics, German C&I Site (Illustrative)
| Parameter | Value |
| Battery capacity | 1 MWh |
| Round-trip efficiency | 90% |
| Annual negative-price charging hours | 450 |
| Average charging cost | −€15/MWh (negative price + fees) |
| Average discharge price (evening peak) | €95/MWh |
| Gross spread per MWh discharged | €110 |
| Annual throughput (cycles × capacity) | ~500 MWh |
| Gross arbitrage revenue | ~€55,000/year |
| Less degradation and O&M | ~€8,000/year |
| Net arbitrage contribution | ~€47,000/year |
This illustrative model assumes a four-hour system and does not include capacity market or ancillary service revenue. Actual results depend on site-specific load profile, grid fees, and market conditions.
Question 2: Can Storage Help Me Get Connected Faster When the Grid Queue Is 455 GW Deep?
The problem. A C&I operator in Spain or Germany seeking a new grid connection faces a queue measured in years. The 455 GW of storage projects waiting for distribution grid access represents a structural bottleneck that will not resolve quickly.
The solution architecture. The answer is not to wait. It is to deploy behind-the-meter storage in a non-export configuration while the grid connection application proceeds. Under non-fixed connection agreements—increasingly available from DSOs in Germany, the Netherlands, and Spain—the storage system can charge from the grid during low-demand periods and discharge to serve on-site load without exporting to the grid. This reduces the site’s maximum import capacity requirement, potentially qualifying the project for a lower connection tier.
For sites with existing grid connections, the constraint is often contracted capacity, not physical connection. A battery system that performs peak shaving can reduce the site’s maximum demand below the contracted threshold, avoiding expensive capacity expansions. In Germany, where grid fees for storage systems commissioned before August 2029 benefit from a 20-year exemption under Section 118(6) EnWG, the economics of behind-the-meter deployment are particularly favourable.
Grid-forming capability adds a second layer of value. In weak-grid areas—common in southern Italy, parts of Spain, and rural regions across Central Europe—a grid-forming inverter can provide voltage and frequency support, making the DSO more willing to approve a connection. The VDE FNN guideline in Germany has moved grid-forming procurement from pilot to market-based, with transmission system operators purchasing inertia services since January 2026.
Question 3: What Does EU Battery Regulation Compliance Actually Require in September 2026?
The problem. The carbon footprint declaration deadline was February 18, 2026. The battery passport deadline is February 18, 2027. Between those dates, customs enforcement has shifted from declaration-based to substantive inspection. Several batches of Chinese-origin storage products have been detained at Rotterdam, with clearance times of 7–14 days for minor documentation issues and three to four weeks for cases requiring re-issuance of third-party verification.
The solution architecture. Compliance is not a single document. It is a three-part evidentiary chain:
1. Carbon footprint declaration calculated according to EU Product Environmental Footprint (PEF) methodology, covering cradle-to-gate lifecycle emissions, verified by an accredited third party. Domestic Chinese calculation reports that use different electricity mix factors or system boundaries are not accepted by customs.
2. Green electricity certificates tied to specific production batches. It is not sufficient to purchase renewable energy certificates at the corporate level. The certificates must demonstrate a direct link between the electricity consumed in manufacturing and the specific battery batch being exported.
3. Critical mineral traceability for lithium, nickel, cobalt, and natural graphite. The due diligence obligation formally applies from August 2027, but downstream buyers are already writing traceability requirements into procurement contracts.
Table 3: EU Battery Regulation Compliance Checklist for C&I Storage Systems
| Requirement | Deadline | Documentation | Common Failure Mode |
| Carbon footprint declaration | Feb. 18, 2026 (in force) | PEF-compliant LCA, third-party verified | Domestic calculation using non-EU electricity factors |
| Green electricity traceability | Enforced from Aug. 2026 | Batch-linked certificates | Certificates not tied to production batches |
| Critical mineral due diligence | Aug. 2027 (legal); earlier in contracts | Supply chain mapping, origin codes | Upstream cell makers unwilling to disclose mine data |
| Digital battery passport | Feb. 18, 2027 | QR code, 71 data points | Incomplete data fields; no system for lifecycle updates |
| Recycling content declaration | — | Material recovery documentation | No European recycling partner network |
Source: EU Regulation 2023/1542; Jiangsu Energy Storage Industry Association disclosures, August–September 2026.
For C&I operators procuring storage systems, the practical question is not “does the supplier have a certificate?” but “can the supplier demonstrate that the certificate applies to this specific batch?” Batch-level traceability is the operational standard that customs now applies.
Question 4: Why Has Fire Safety Design Changed—and What Does It Mean for My Installation?
The problem. ISO 3941:2026 introduced Class L as a dedicated fire classification for lithium-ion battery fires, recognising that these fires behave fundamentally differently from Class A, B, or electrical fires. The standard identifies specific hazards: higher energy density leading to faster heat release, cell-to-cell thermal runaway propagation, toxic and flammable gas release, explosion risk from constrained vented gas, and delayed re-ignition from stranded electrical energy.
The practical consequence is a paradigm shift. The European fire safety consensus—reflected in guidance from ACP, EASE, and France’s DGSCGC—now prioritises controlled burn and boundary cooling over aggressive suppression. Water, the traditional universal extinguishing agent, has three critical limitations in Class L events: contaminated runoff requiring containment, DC conductivity risk to responders, and incomplete suppression leading to re-ignition hours later.
The solution architecture. A compliant C&I storage installation in 2026 must demonstrate:
- UL 9540A sixth edition large-scale fire testing (LSFT) data for the specific enclosure configuration deployed.
- Multi-layer aerogel thermal barriers that extend the time between cell-to-cell propagation, providing evacuation and emergency response windows.
- Installation spacing that satisfies both local fire department requirements and insurer risk assessments. The Class L classification means that fire risk assessors will now specifically evaluate lithium battery presence, type, and quantity in commercial and industrial premises.
- Hazard mitigation analysis documentation supporting the permitting application.
For outdoor cabinet systems, the design must account for the reality that the fire will not be extinguished. The objective is to contain it within the enclosure, prevent propagation to adjacent units, and manage gas venting safely. Liquid-cooled outdoor cabinets with integrated aerosol or inert gas suppression and aerogel barriers between cell modules represent the current state of compliant design.
Question 5: How Do I Configure a System That Qualifies for Capacity Markets and Serves My C&I Load?
The problem. Germany’s capacity market requires 10-hour discharge duration for battery participation. A conventional C&I storage system designed for peak shaving is typically two hours. A 10-hour system sized for capacity market eligibility may be significantly oversized for the site’s daily load profile.
The solution architecture. The answer is modular multi-duration configuration. A containerised system with 2–8 hour flexibility allows the operator to:
- Deploy 2-hour capacity for daily peak shaving and negative-price arbitrage.
- Extend to 4–6 hours for participation in regional flexibility markets.
- Configure for 8+ hours where capacity market qualification is the primary revenue objective.
The EMS must manage concurrent revenue streams: capacity market availability commitments, day-ahead and intraday arbitrage, and on-site demand management. These are not mutually exclusive, but they require sophisticated scheduling logic. A system that commits to 10-hour discharge availability cannot simultaneously cycle for arbitrage on the same capacity.
Table 4: Multi-Revenue Configuration Scenarios
| Configuration | Primary Revenue | Secondary Revenue | Capacity Market Eligible? | Typical C&I Use Case |
| 2h / 1 MWh | Peak shaving, arbitrage | — | No | Warehouse, retail, small industrial |
| 4h / 2 MWh | Arbitrage + demand management | FCR/FRR | No (Germany); Yes (Spain, Italy) | Manufacturing, cold storage |
| 6h / 3 MWh | Multi-market optimisation | Capacity (Spain/Italy) | Partial | Large industrial, district energy |
| 8h+ / 5 MWh+ | Capacity market primary | Arbitrage secondary | Yes (Germany 10h req.) | Utility-scale, data centre |
Note: German capacity market requires 10h minimum. Spanish and Italian mechanisms have different duration requirements. Configuration should be designed against the specific market mechanism targeted.
For C&I operators evaluating capacity market participation, the decision is often not whether to build a 10-hour system, but whether to build a modular system that can scale to 10-hour equivalent duration through additional container units. This preserves optionality without overcapitalising on a single revenue stream.
Question 6: What Are the Real Constraints on Outdoor Cabinet Deployment in European C&I Settings?
The problem. European C&I users have storage demand. What they often lack is suitable installation space. The constraints are not technical—they are spatial, regulatory, and environmental: fire spacing requirements, building setbacks, noise limits, community acceptance, construction windows, and available electrical capacity at the point of interconnection.
The solution architecture. The outdoor cabinet format addresses these constraints through compact footprint and modular deployment. A liquid-cooled cabinet rated at 100 kW / 232 kWh occupies approximately 1.6 m × 1.35 m × 2.3 m—roughly the footprint of a large industrial refrigerator. Multiple units can be installed in a row with spacing determined by fire code, not by system architecture.
Table 5: Outdoor Cabinet Deployment Considerations
| Constraint | Typical Requirement | Design Response |
| Fire spacing | 1–3 m between units (varies by jurisdiction) | Modular layout; fire-rated barriers between cabinets |
| Noise | 55–65 dB(A) at 1 m | Liquid cooling reduces fan noise vs. air cooling |
| Operating temperature | −20°C to +50°C | Liquid thermal management stabilises cell temperature |
| Installation time | 1–2 days per unit | Pre-assembled, factory-tested, plug-and-play connections |
| Electrical interface | 400 V AC, 3-phase | Standard industrial connection; no HV infrastructure |
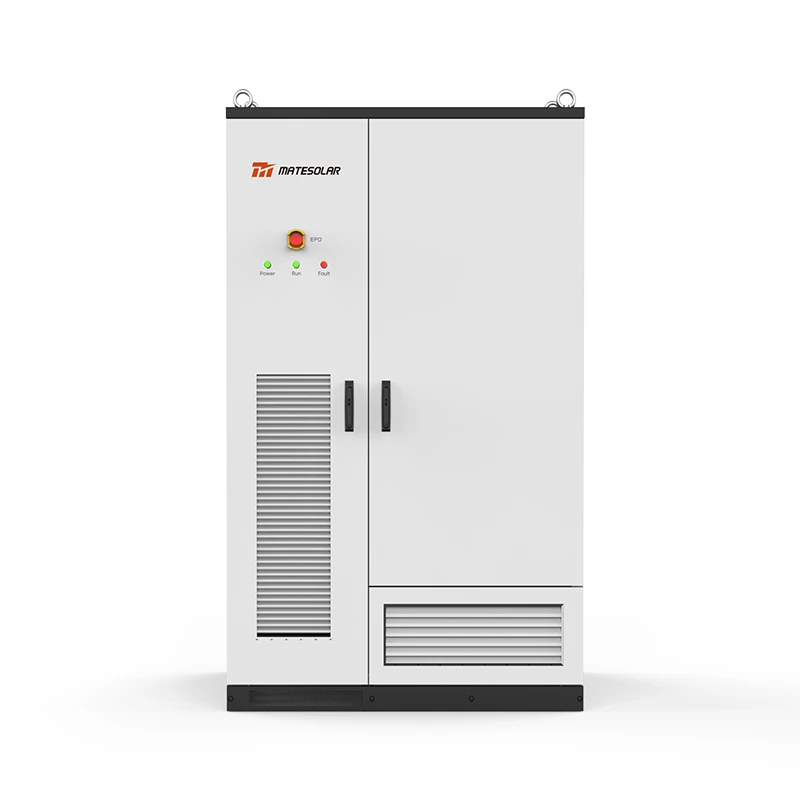
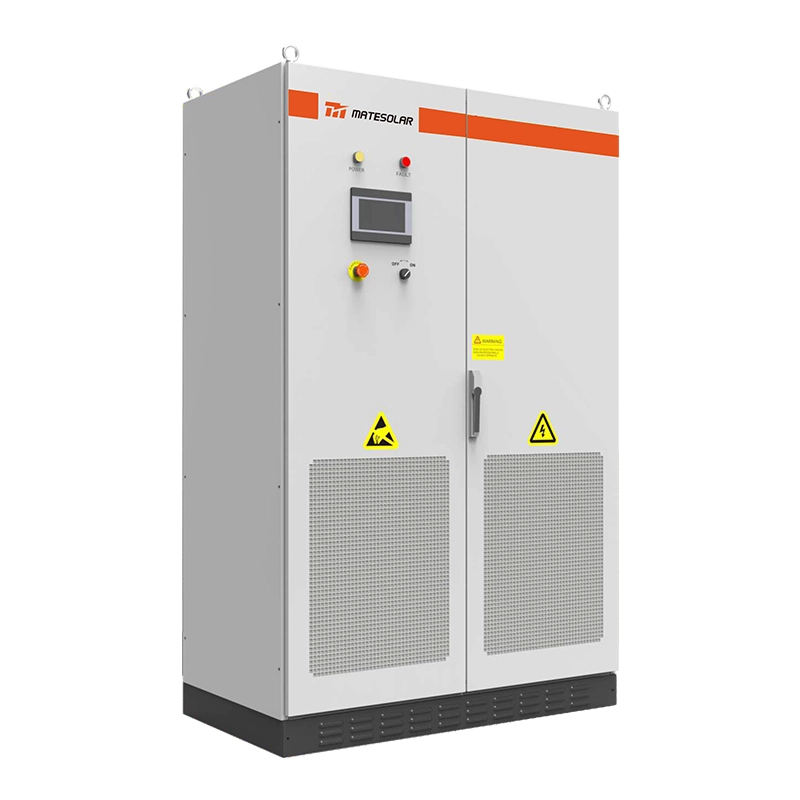
For sites with limited space or restricted construction windows, the 100kW/232kWh and 125kW/261kWh Liquid-Cooled Outdoor Cabinet Energy Storage System is configured for rapid deployment: factory-assembled, pre-tested, and delivered as a complete unit requiring only foundation preparation, electrical connection, and commissioning. The liquid cooling architecture addresses the thermal management challenge of 314 Ah and higher cell formats, maintaining cell temperature uniformity without the acoustic and spatial footprint of air-cooled alternatives.
Question 7: How Does Storage Solve the AI Data Centre Power Problem?
The problem. European data centre operators face a grid connection queue that reaches 7–10 years in major markets. Amazon Web Services has publicly confirmed a seven-year wait for new European data centre grid connections. Simultaneously, the EU’s 2030 100% renewable electricity mandate for data centres creates a compliance deadline that cannot be met through grid procurement alone.
The solution architecture. Data centre storage deployments in 2026 follow two models:
Model 1: Grid-connected peak shaving. A battery system sized for 4–8 hours of discharge reduces the site’s maximum grid import capacity. This allows the facility to operate above its contracted grid connection limit during peak computing loads, effectively increasing capacity without waiting for a grid upgrade. Co-located solar PV and battery storage allow edge data centres to operate above local grid connection limits through peak shaving.
Model 2: Green power direct connection. On-site renewable generation—solar, wind, or both—connects directly to the data centre load through a battery buffer, with the grid serving as backup rather than primary supply. Envision’s Galaxy Campus in Ulanqab demonstrates the model at gigawatt scale: a directly connected renewable energy AI data centre. For European deployments, the regulatory pathway for direct connection is evolving, but several member states now permit private wire arrangements for industrial loads.
The critical requirement for data centre storage is availability. A battery system supporting a Tier IV data centre must deliver 99.999% uptime. This requires N+1 redundancy at the PCS level, hot-swappable battery modules, and EMS logic that prioritises load support over market optimisation when the data centre is operating at capacity.
Question 8: How Real Is the “Made in EU” Requirement for Storage Projects?
The problem. The EU’s Industrial Accelerator Act (IAA), proposed in March 2026 and now in parliamentary review, introduces strict local content requirements for battery and storage technologies. For battery systems of 1 MWh or larger, the IAA would require incorporation of a European-made energy management system one year after entry into force, with broader local content thresholds applying after three years. The German capacity market already includes local content rules: key components including battery cells and inverters must be produced in the EU or in countries with EU free trade agreements.
The solution architecture. The supply chain response has already begun. CATL’s joint venture with Stellantis in Zaragoza, Spain—a €4.1 billion investment—is scheduled to begin production by the end of 2026. Hithium signed a memorandum with the Navarra regional government in April 2026 for a €400 million battery cell and system manufacturing facility, expected to begin production by the end of 2027.
For C&I operators, the practical implication is a supplier qualification question: does the supplier have a credible pathway to EU-origin cell and system supply within the project’s financing horizon? A project financed on 15-year capacity market contracts cannot rely on a supply chain that will be non-compliant in three years.
Question 9: What Makes an EMS “Intelligent” in the 2026 Market?
The problem. The difference between a profitable and unprofitable C&I storage installation increasingly lies in the EMS, not the battery. A system that follows a fixed charge-discharge schedule captures a fraction of the value available to a system that responds to market signals in real time.
The solution architecture. A compliant EMS for European C&I applications in 2026 must:
- Ingest day-ahead and intraday prices from EPEX SPOT, Nord Pool, or the relevant regional exchange.
- Forecast site load using historical consumption data, production schedules, and weather inputs.
- Optimise across multiple value streams: negative-price charging, peak shaving, capacity market availability, and frequency response.
- Provide grid-forming capability where the site is in a weak-grid area or where the DSO requires it as a connection condition.
- Interface with building systems: heat pumps, EV chargers, and building management systems, to coordinate load and generation.
The EMS is not a dashboard. It is the revenue engine of the storage asset. A system with excellent batteries and a mediocre EMS will underperform a system with adequate batteries and an excellent EMS.
Question 10: When Does Grid-Forming Capability Become a Requirement Rather Than a Feature?
The problem. Europe’s grid is losing inertia as synchronous generation retires. Weak-grid nodes—common in rural areas, islands, and regions with high renewable penetration—struggle to maintain voltage and frequency stability. A conventional grid-following inverter cannot operate reliably in these conditions and may exacerbate instability.
The solution architecture. Grid-forming inverters establish their own voltage and frequency reference rather than following the grid’s lead. This enables:
- Stable operation in weak grids (short-circuit ratio below 2).
- Virtual inertia provision, supporting frequency stability during disturbances.
- Black start capability, allowing the storage system to energise a de-energised network.
- Islanded operation for critical loads when the grid fails.
In Germany, transmission system operators began market-based procurement of inertia (instantaneous reserve) in January 2026, creating a revenue stream for grid-forming assets. In Spain, the April 2025 blackout elevated grid-forming storage from a technical curiosity to a system security priority.
For C&I operators, the decision framework is straightforward: if the site is in a weak-grid area, if the DSO requires grid-forming as a connection condition, or if the site has critical loads that must ride through grid disturbances, grid-forming capability is not optional.
Question 11: How Do I Model Multi-Market Revenue When Every Market Has Different Rules?
The problem. A C&I storage asset in Germany can potentially earn revenue from: day-ahead arbitrage, intraday arbitrage, frequency containment reserve (FCR), automatic frequency restoration reserve (aFRR), capacity market availability, and on-site demand management. Each market has different qualification requirements, dispatch obligations, and payment structures. The complexity is paralysing for operators without dedicated energy trading teams.
The solution architecture. The approach that works in 2026 is primary-plus-secondary revenue stacking:
1. Identify the primary revenue stream that determines the system’s core configuration: capacity market participation (long duration, high availability), arbitrage (cycling flexibility), or demand management (load-following).
2. Layer secondary revenue streams that are compatible with the primary stream’s dispatch profile.
3. Use the EMS to manage conflicts: a capacity market commitment reduces the capacity available for arbitrage; the EMS must schedule charge/discharge to satisfy availability obligations while capturing arbitrage value when possible.
Table 6: Revenue Stacking Compatibility Matrix (German C&I Example)
| Primary Revenue | Compatible Secondary | Incompatible | EMS Complexity |
| Capacity market (10h) | FCR, demand management | Intraday arbitrage (conflicts with availability) | High |
| Day-ahead arbitrage | Intraday, demand management, aFRR | Capacity market (duration mismatch) | Medium |
| Demand management | Arbitrage (opportunistic), FCR | Capacity market (availability conflict) | Low–Medium |
Note: This matrix is illustrative. Actual compatibility depends on specific market rules and contract terms.
Question 12: What Happens to the Battery at End of Life?
The problem. The EU Battery Regulation requires digital battery passports for industrial batteries above 2 kWh from February 2027. The passport must contain 71 data points covering identity, technical characteristics, environmental impact, and lifecycle information. But the passport is only as good as the recycling infrastructure behind it. Germany has a highly organised recycling management system; other member states are still developing collection and processing capacity.
The solution architecture. A compliant end-of-life strategy for C&I storage in 2026 requires:
- Battery passport data management from the point of manufacture, with the ability to update the passport as the battery moves through its lifecycle.
- European recycling partnerships that can accept industrial batteries and provide documentation of material recovery.
- Recycled content declaration capability, as the regulation’s recycled content requirements phase in.
- Warranty terms that cover capacity degradation and thermal events, providing the operator with recourse if the system underperforms.
For operators, the practical question is not “can this battery be recycled?” but “does my supplier have a documented, auditable pathway for recycling this specific battery model in the European market?”
Part III: From Questions to Deployment—The Product Architecture That Answers Them
The twelve questions above do not have abstract answers. They have physical deployment implications. A C&I storage installation in September 2026 must be configured to address the specific combination of market conditions, regulatory requirements, and site constraints that the operator faces.
3.1 The Deployment Decision Tree
Step 1: What is the primary revenue objective?
- Negative-price arbitrage and peak shaving → 2–4 hour system, high cycling capability, EMS with market price integration.
- Capacity market participation → 8–10+ hour system, high availability, local content compliance, modular design for duration extension.
- Data centre or critical load support → 4–8 hour system, N+1 redundancy, grid-forming capability, 99.999% availability architecture.
Step 2: What are the site constraints?
- Limited footprint → outdoor cabinet format, liquid-cooled for high energy density.
- Rapid deployment required → containerised system, factory-tested, plug-and-play.
- Weak grid or islanded operation → grid-forming inverter, black start capability.
Step 3: What is the compliance requirement?
- EU market access → PEF-compliant carbon footprint declaration, batch-level green electricity traceability, battery passport-ready data management.
- Capacity market participation → local content verification, duration certification, availability guarantees.
3.2 The Product Portfolio That Matches These Requirements
For C&I operators navigating this decision tree, the appropriate hardware configuration depends on scale, site conditions, and revenue strategy.
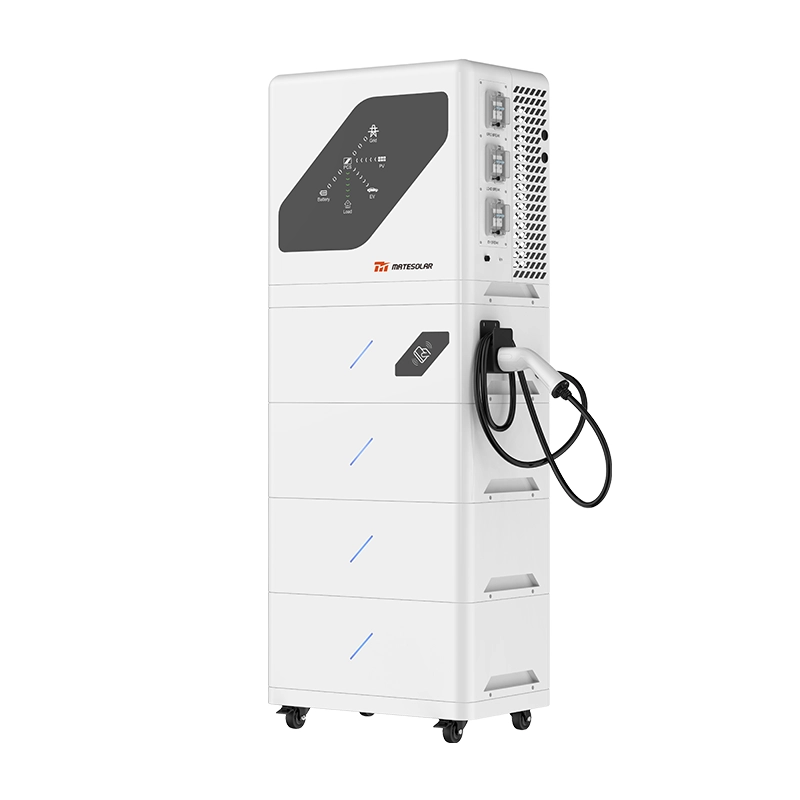
Smaller C&I sites (100–500 kW demand): Outdoor cabinet systems provide the compact footprint, modular scalability, and liquid-cooled thermal management required for European deployment. The 100kW/232kWh and 125kW/261kWh Liquid-Cooled Outdoor Cabinet Energy Storage System is designed for sites where installation space is constrained and rapid deployment is a priority. The liquid cooling architecture maintains cell temperature uniformity under high cycling rates, addressing the thermal management challenge of modern high-density cell formats. For sites where the primary revenue objective is negative-price arbitrage and daily peak shaving, this format provides the cycling flexibility without the footprint of a containerised system.
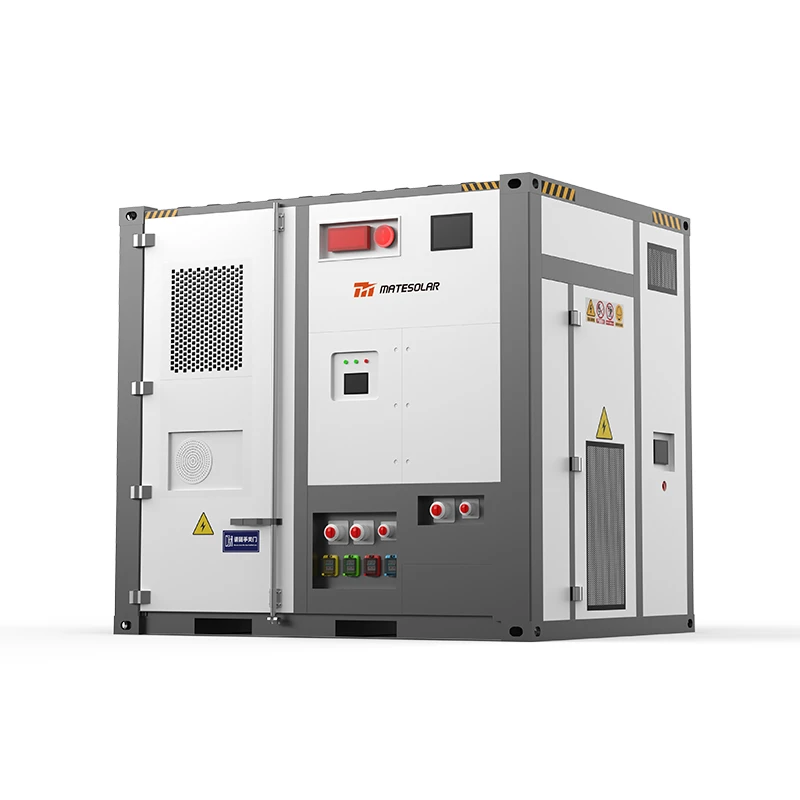
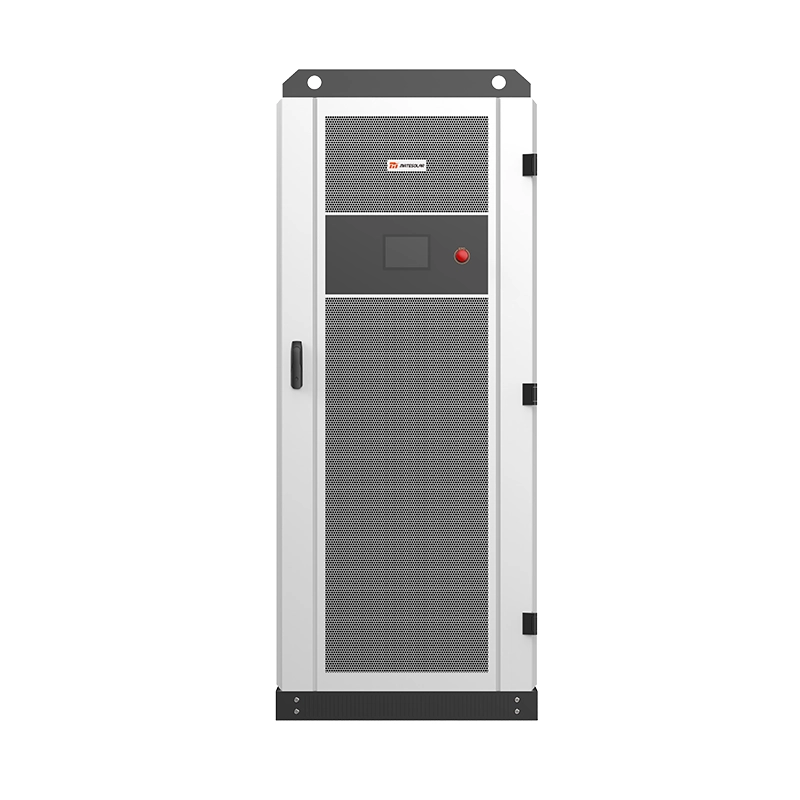
Medium C&I and light industrial sites (500 kW–2 MW demand): Containerised systems offer higher energy density and lower cost per kWh for larger installations. The 40Ft 1MWh / 2MWh Air-Cooled Container ESS is configured for sites with available outdoor space and a deployment timeline that permits standard container installation. Air cooling is appropriate for moderate-climate sites with lower cycling intensity; the container format supports multi-unit configurations for duration extension.
Large industrial and data centre applications (2 MW+ demand): High-density liquid-cooled containers provide the energy density, thermal performance, and cycling capability required for intensive applications. The 20ft 3MWh / 5MWh Liquid Cooling Container ESS is designed for sites where space efficiency and thermal management are critical—including data centre deployments where the storage system operates in a controlled environment with high availability requirements. The liquid cooling system enables higher continuous power output and faster response times compared to air-cooled alternatives.
For sites integrating solar generation with storage—whether for self-consumption, arbitrage, or green power direct connection—the Commercial 500KW Hybrid Solar System provides an integrated PV-plus-storage architecture with a single control layer. This configuration is particularly relevant for C&I operators seeking to maximise self-consumption while retaining the flexibility to participate in grid markets.
Part IV: Frequently Asked Questions
Q: My site has a 2-hour peak demand period. Do I really need a 10-hour battery for the German capacity market?
A: Not necessarily—but you need to decide whether capacity market participation is a primary or secondary revenue objective. A 2-hour system optimised for peak shaving can generate returns from demand management and arbitrage. A 10-hour system opens capacity market eligibility but requires significantly higher capital investment and may be oversized for the site’s daily load profile. The modular approach—starting with 2–4 hours and adding container units for duration extension—preserves optionality.
Q: The carbon footprint declaration deadline was February 2026. Is my existing system compliant?
A: Compliance depends on whether the declaration was calculated using EU PEF methodology and verified by an accredited third party. Declarations prepared using domestic Chinese calculation methods or electricity mix factors are not accepted by EU customs. If you have existing inventory in Europe or are planning shipments, verify the methodology used for the declaration before the shipment arrives at port.
Q: How long does it take to deploy a containerised system from order to commissioning?
A: Manufacturing and delivery timelines vary by configuration and supplier. Factory-assembled, pre-tested systems can typically be delivered within 8–12 weeks for standard configurations, with additional time required for shipping, site preparation, and commissioning. For large-scale projects with on-site technical support requirements, commissioning timelines should be factored into the project schedule from the outset.
Q: What technical support is available if I encounter a hardware or software issue?
A: Support models vary by project scale and location. For software and EMS issues, remote technical support can typically resolve configuration problems, firmware updates, and optimisation logic adjustments. For hardware issues, replacement components can be shipped with installation guidance, or in more significant cases, product replacement may be arranged. For large-scale C&I projects, on-site technical support for commissioning and debugging can be arranged where the project scope warrants it.
Q: Does grid-forming capability add significant cost to a C&I storage system?
A: The cost premium for grid-forming inverters has narrowed considerably as the technology has matured. For sites where grid-forming is required by the DSO as a connection condition, or where the site has critical loads requiring ride-through capability, the incremental cost is often justified by avoided grid upgrade costs or enhanced resilience. For sites in strong-grid areas with non-critical loads, grid-following may remain the more cost-effective choice.
Q: How do I know whether my site is in a “weak grid” area?
A: The short-circuit ratio (SCR) at the point of connection is the standard metric. An SCR below 2–3 typically indicates a weak grid where grid-following inverters may experience stability issues. Your DSO can provide the SCR for the connection point, or a power system study can assess it. In practice, if the DSO raises stability concerns during the connection application process, that is a strong signal that grid-forming capability will be required or recommended.
Q: What happens if the battery passport deadline arrives and my system does not have one?
A: From February 18, 2027, industrial batteries above 2 kWh placed on the EU market must carry a digital battery passport accessible via QR code. Systems already in service before that date may have different obligations depending on their market placement status. For new deployments, the passport should be treated as a procurement requirement: the supplier must demonstrate the ability to generate and maintain passport data throughout the battery’s lifecycle.
Q: Can I participate in multiple capacity markets across different countries?
A: Capacity market participation is generally tied to the physical location of the asset. A storage system in Germany participates in the German capacity market; a system in Spain participates in the Spanish mechanism. Cross-border participation is not currently available for behind-the-meter C&I storage. The practical strategy is to select the market mechanism that best matches the site’s location and the system’s technical configuration.
Q: What is the expected degradation rate for a C&I battery system over a 10-year horizon?
A: Degradation depends on chemistry, cycling intensity, depth of discharge, and thermal management. Modern lithium iron phosphate (LFP) systems deployed in C&I applications typically warrant 70–80% of original capacity after 6,000–8,000 full cycles, which corresponds to 10–15 years of daily cycling. Liquid cooling extends cycle life by maintaining cell temperature uniformity and reducing thermal stress. The specific warranty terms offered by the supplier are the definitive reference.
Q: Is there a risk that the EU will further tighten local content requirements after the IAA is finalised?
A: Yes. The IAA proposal already includes a phased local content pathway, with requirements becoming more stringent over three years from entry into force. Suppliers and operators should assume that local content requirements will tighten, not relax. Procurement decisions should favour suppliers with credible EU manufacturing or assembly plans, and projects should include contractual provisions for supply chain compliance over the asset’s operational life.
Part V: The Strategic Picture—What This Means for C&I Operators in Late 2026
The European C&I storage market in September 2026 is not a market of unlimited opportunity. It is a market of specific, conditional opportunities. The conditions are defined by negative prices, grid congestion, capacity market rules, battery regulation compliance, and fire safety standards. Operators who understand these conditions—and configure their systems accordingly—will capture value. Operators who treat storage as a generic “battery in a box” will underperform.
Three strategic conclusions follow from the analysis in this guide:
First, the EMS is the asset. Battery cells are increasingly commoditised. The differentiation lies in the control layer that decides when to charge, when to discharge, and how to balance multiple revenue streams against site load requirements. A C&I storage project should be evaluated on its EMS capability as much as its battery specification.
Second, compliance is a procurement criterion, not an afterthought. The carbon footprint declaration, battery passport, and local content requirements are not administrative overhead. They are market access conditions. A storage system that cannot demonstrate batch-level green electricity traceability or PEF-compliant carbon accounting is a storage system that may not clear customs.
Third, modularity preserves optionality. The market rules are evolving—capacity market duration requirements, grid fee structures, local content thresholds. A storage system that can be reconfigured or extended as rules change is more valuable than a system optimised for today’s rules alone.
Conclusion: The Questions That Matter, and the Answers That Work
The European C&I storage market in September 2026 rewards operators who ask precise questions. Not “is storage worth it?” but “what duration and configuration optimises my revenue under the German capacity market rules?” Not “is my battery compliant?” but “can I demonstrate batch-level carbon footprint traceability at the port of entry?” Not “does my EMS work?” but “can my EMS simultaneously manage negative-price arbitrage, peak shaving, and capacity market availability?”
The answers to these questions are not abstract. They are embedded in system configuration, EMS logic, compliance documentation, and deployment strategy. They are the difference between a project that proceeds and a project that stalls.
For operators navigating this landscape, the starting point is a clear assessment of the site’s constraints, the market’s opportunities, and the regulatory requirements. From there, the system configuration follows.
MateSolar is a one-stop PV and energy storage solutions provider, supporting C&I operators across Europe with integrated solar-plus-storage architectures, liquid-cooled and air-cooled container systems, and outdoor cabinet solutions configured for the specific demands of the 2026 market. From negative-price arbitrage to capacity market qualification, from grid-forming capability to EU Battery Regulation compliance, MateSolar’s portfolio is designed to answer the questions that determine whether a C&I storage project succeeds.
For configuration guidance and deployment planning, explore the product pages linked throughout this guide or contact the MateSolar team directly.